- Chinese automakers surged in Europe during August with registrations up 111% year-on-year to 97,639 units, reflecting aggressive expansion and channel partnerships pressuring incumbents.
- BYD registered 26,007 units in August and 234,099 units January–August, while Leapmotor hit 7,630 units in August and 73,297 year-to-date, showing strong volume gains.
- Competition targets mainstream EV buyers from Volkswagen, Renault and others, but risks include scaling dealer networks, delivery timing, and margin pressure from rapid volume growth.
The European Automobile Manufacturers’ Association (ACEA) released data on Sept. 24 covering new vehicle registrations in the European Union and Europe for August 2026.
In August, new-car registrations across Europe, including the EU, the UK and EFTA, reached 832,637 units, up 5.3% year on year.
In the first eight months of the year, registrations totaled 9,192,500 units, up 5.8% YoY.
In the EU alone, new-car registrations reached 708,211 units in August, up 4.5% YoY, further pointing to a recovery in the market.

New-energy vehicles were the main driver of growth in the European auto market.
In August, battery-electric vehicles (BEVs) accounted for 29.2% of registrations across Europe, while plug-in hybrids (PHEVs) took an 11.3% share.
Hybrid-electric vehicles (HEVs), meanwhile, remained the preferred powertrain among European consumers, accounting for 32.8% of registrations in August.
Traditional internal-combustion vehicles continued to come under pressure.
In August, petrol and diesel vehicles combined accounted for just 24.3% of the market, down sharply from 33.5% a year earlier.

Chinese brands were the most prominent variable in this latest growth cycle.
Dataforce data showed that Chinese brands collectively registered 97,639 vehicles in Europe in August, up 111% YoY, lifting their market share from 7.1% a year earlier to a record 11.7%.
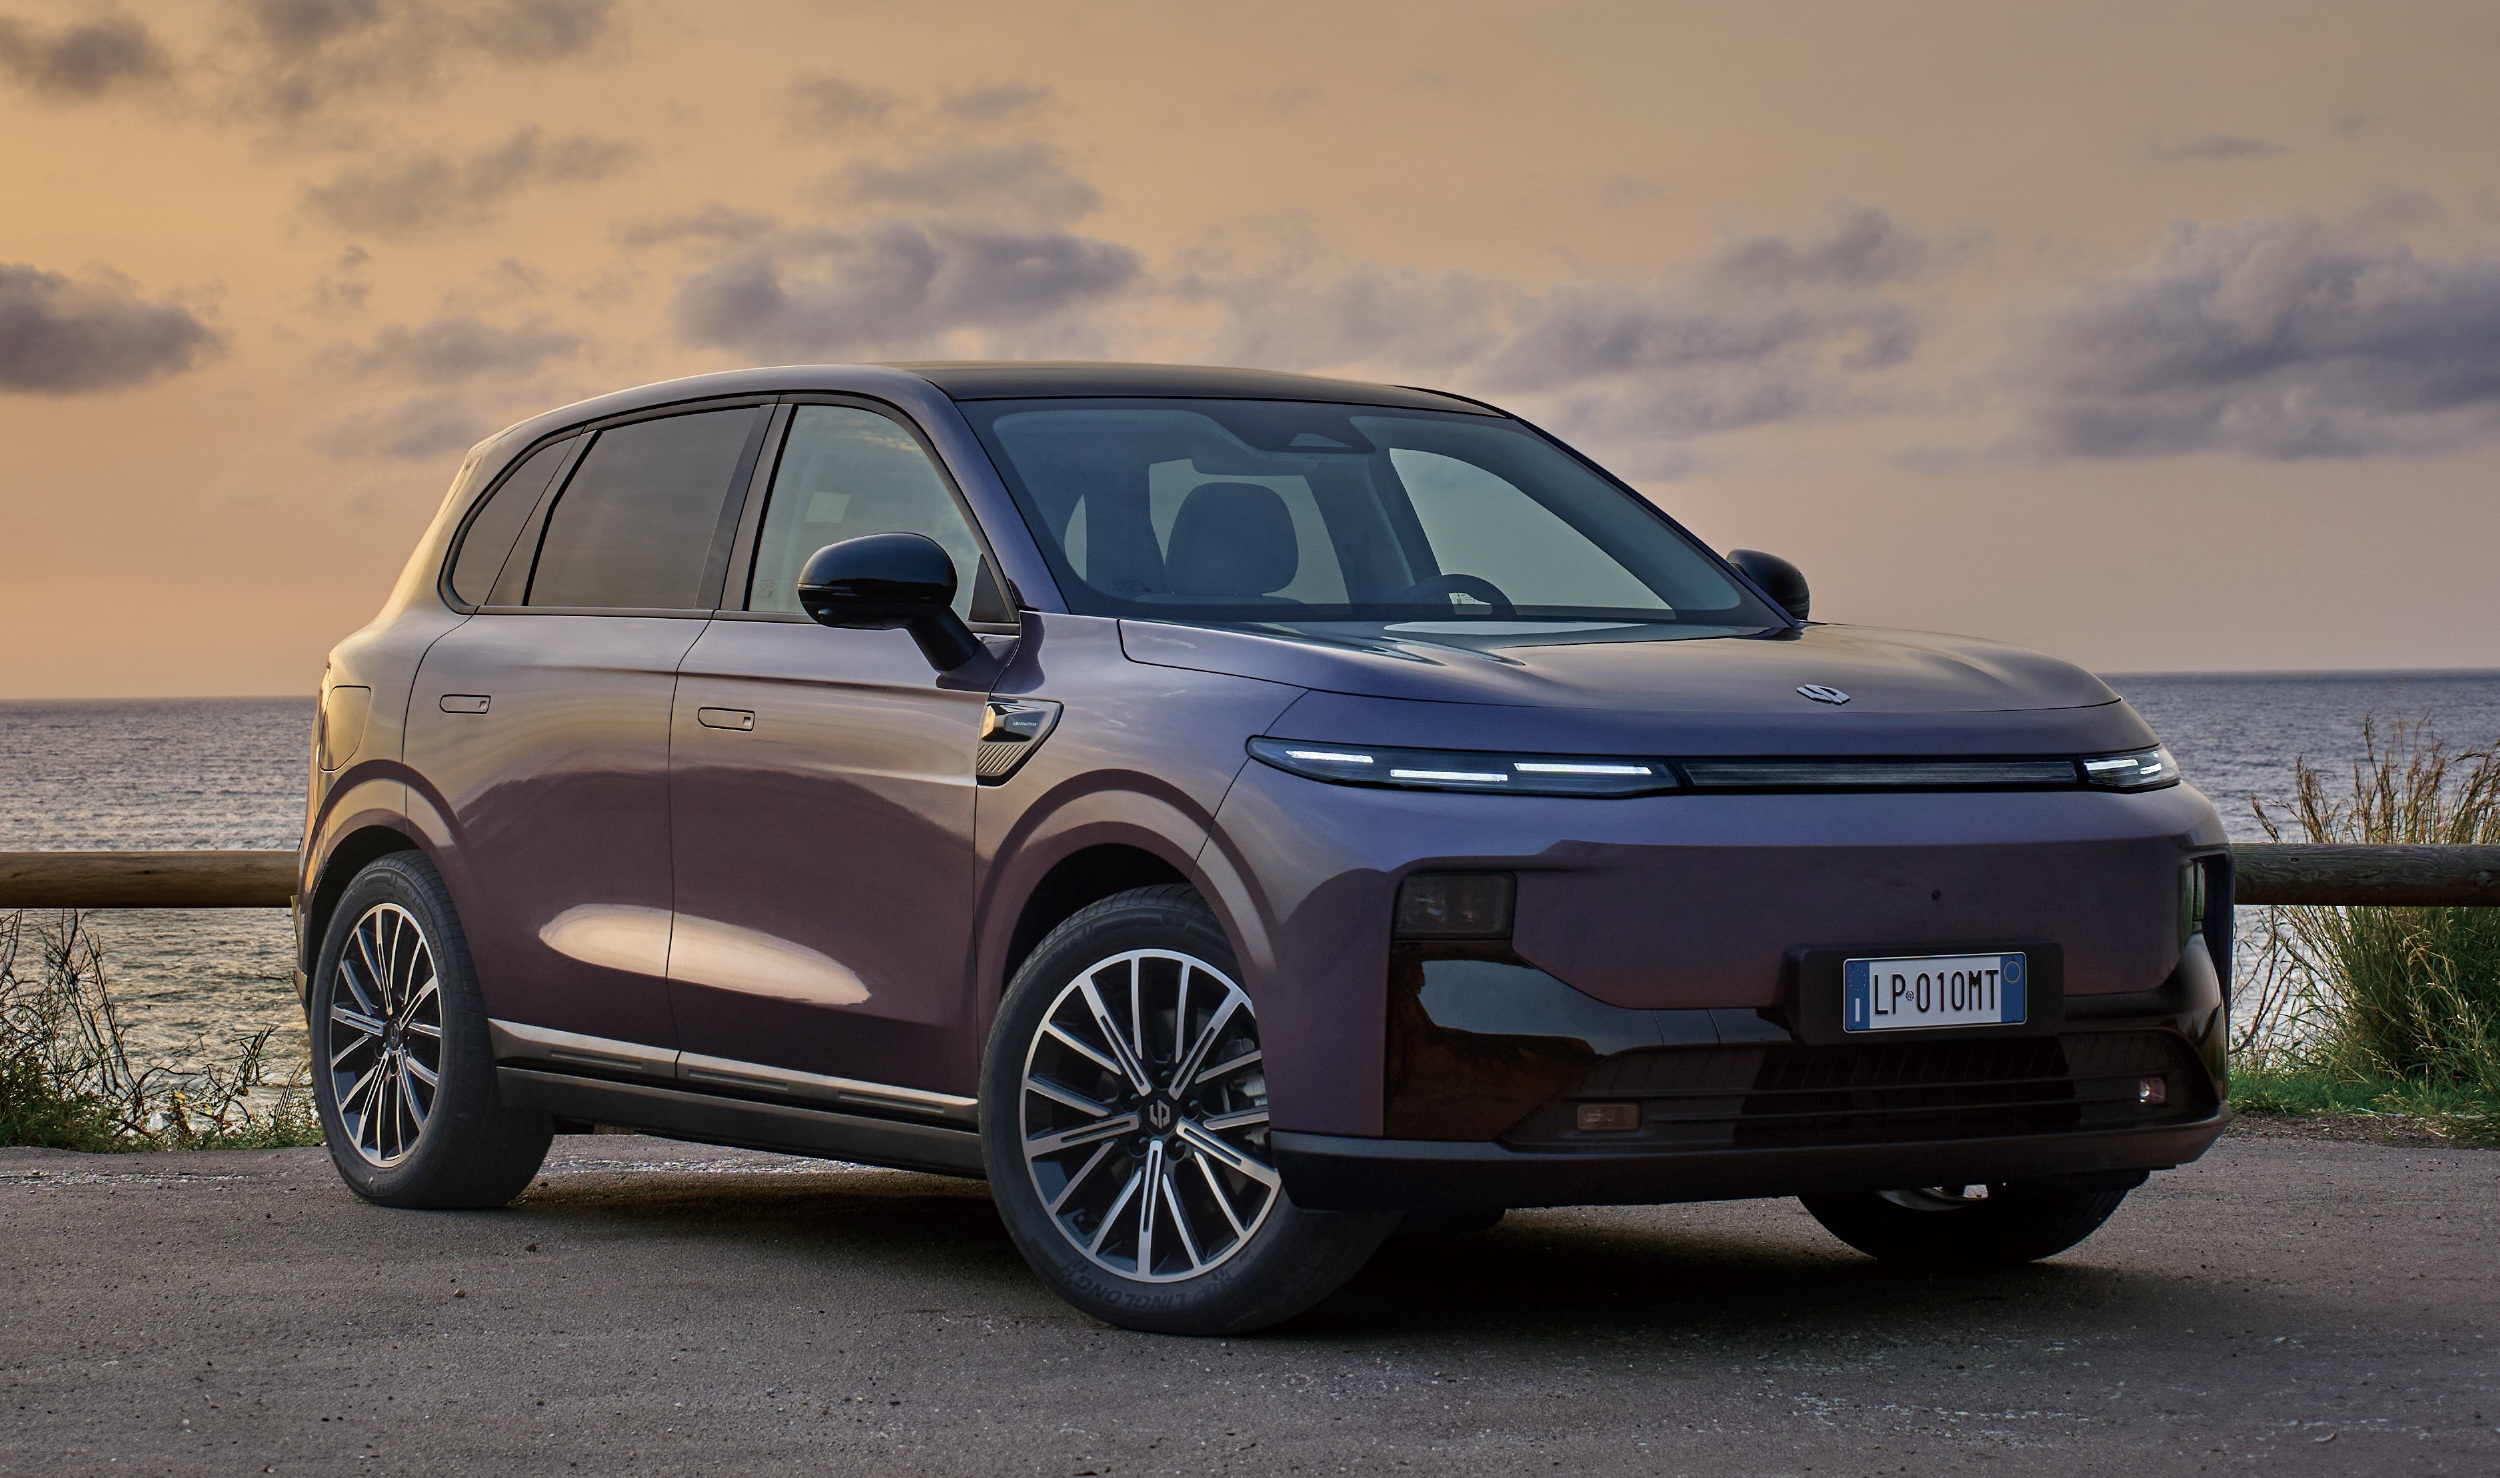
Leapmotor was among the fastest-growing Chinese brands. Its European registrations reached 7,630 units in August, up 219.5% YoY, while registrations for the first eight months totaled 73,297 units, up 449.9%.
The growth has been supported by its distribution partnership with Stellantis.
As of Sept. 22, Leapmotor International had 1,020 sales outlets across Europe, covering 36 countries and about 80% of the European region.
ACEA data showed that Stellantis and Leapmotor together accounted for a 15.6% share of the EU, EFTA and UK markets in January-August.
BYD was the highest-selling Chinese brand in August. Its European registrations reached 26,007 units, up 127.9% YoY, while the January-August total reached 234,099 units, up 144.1%.
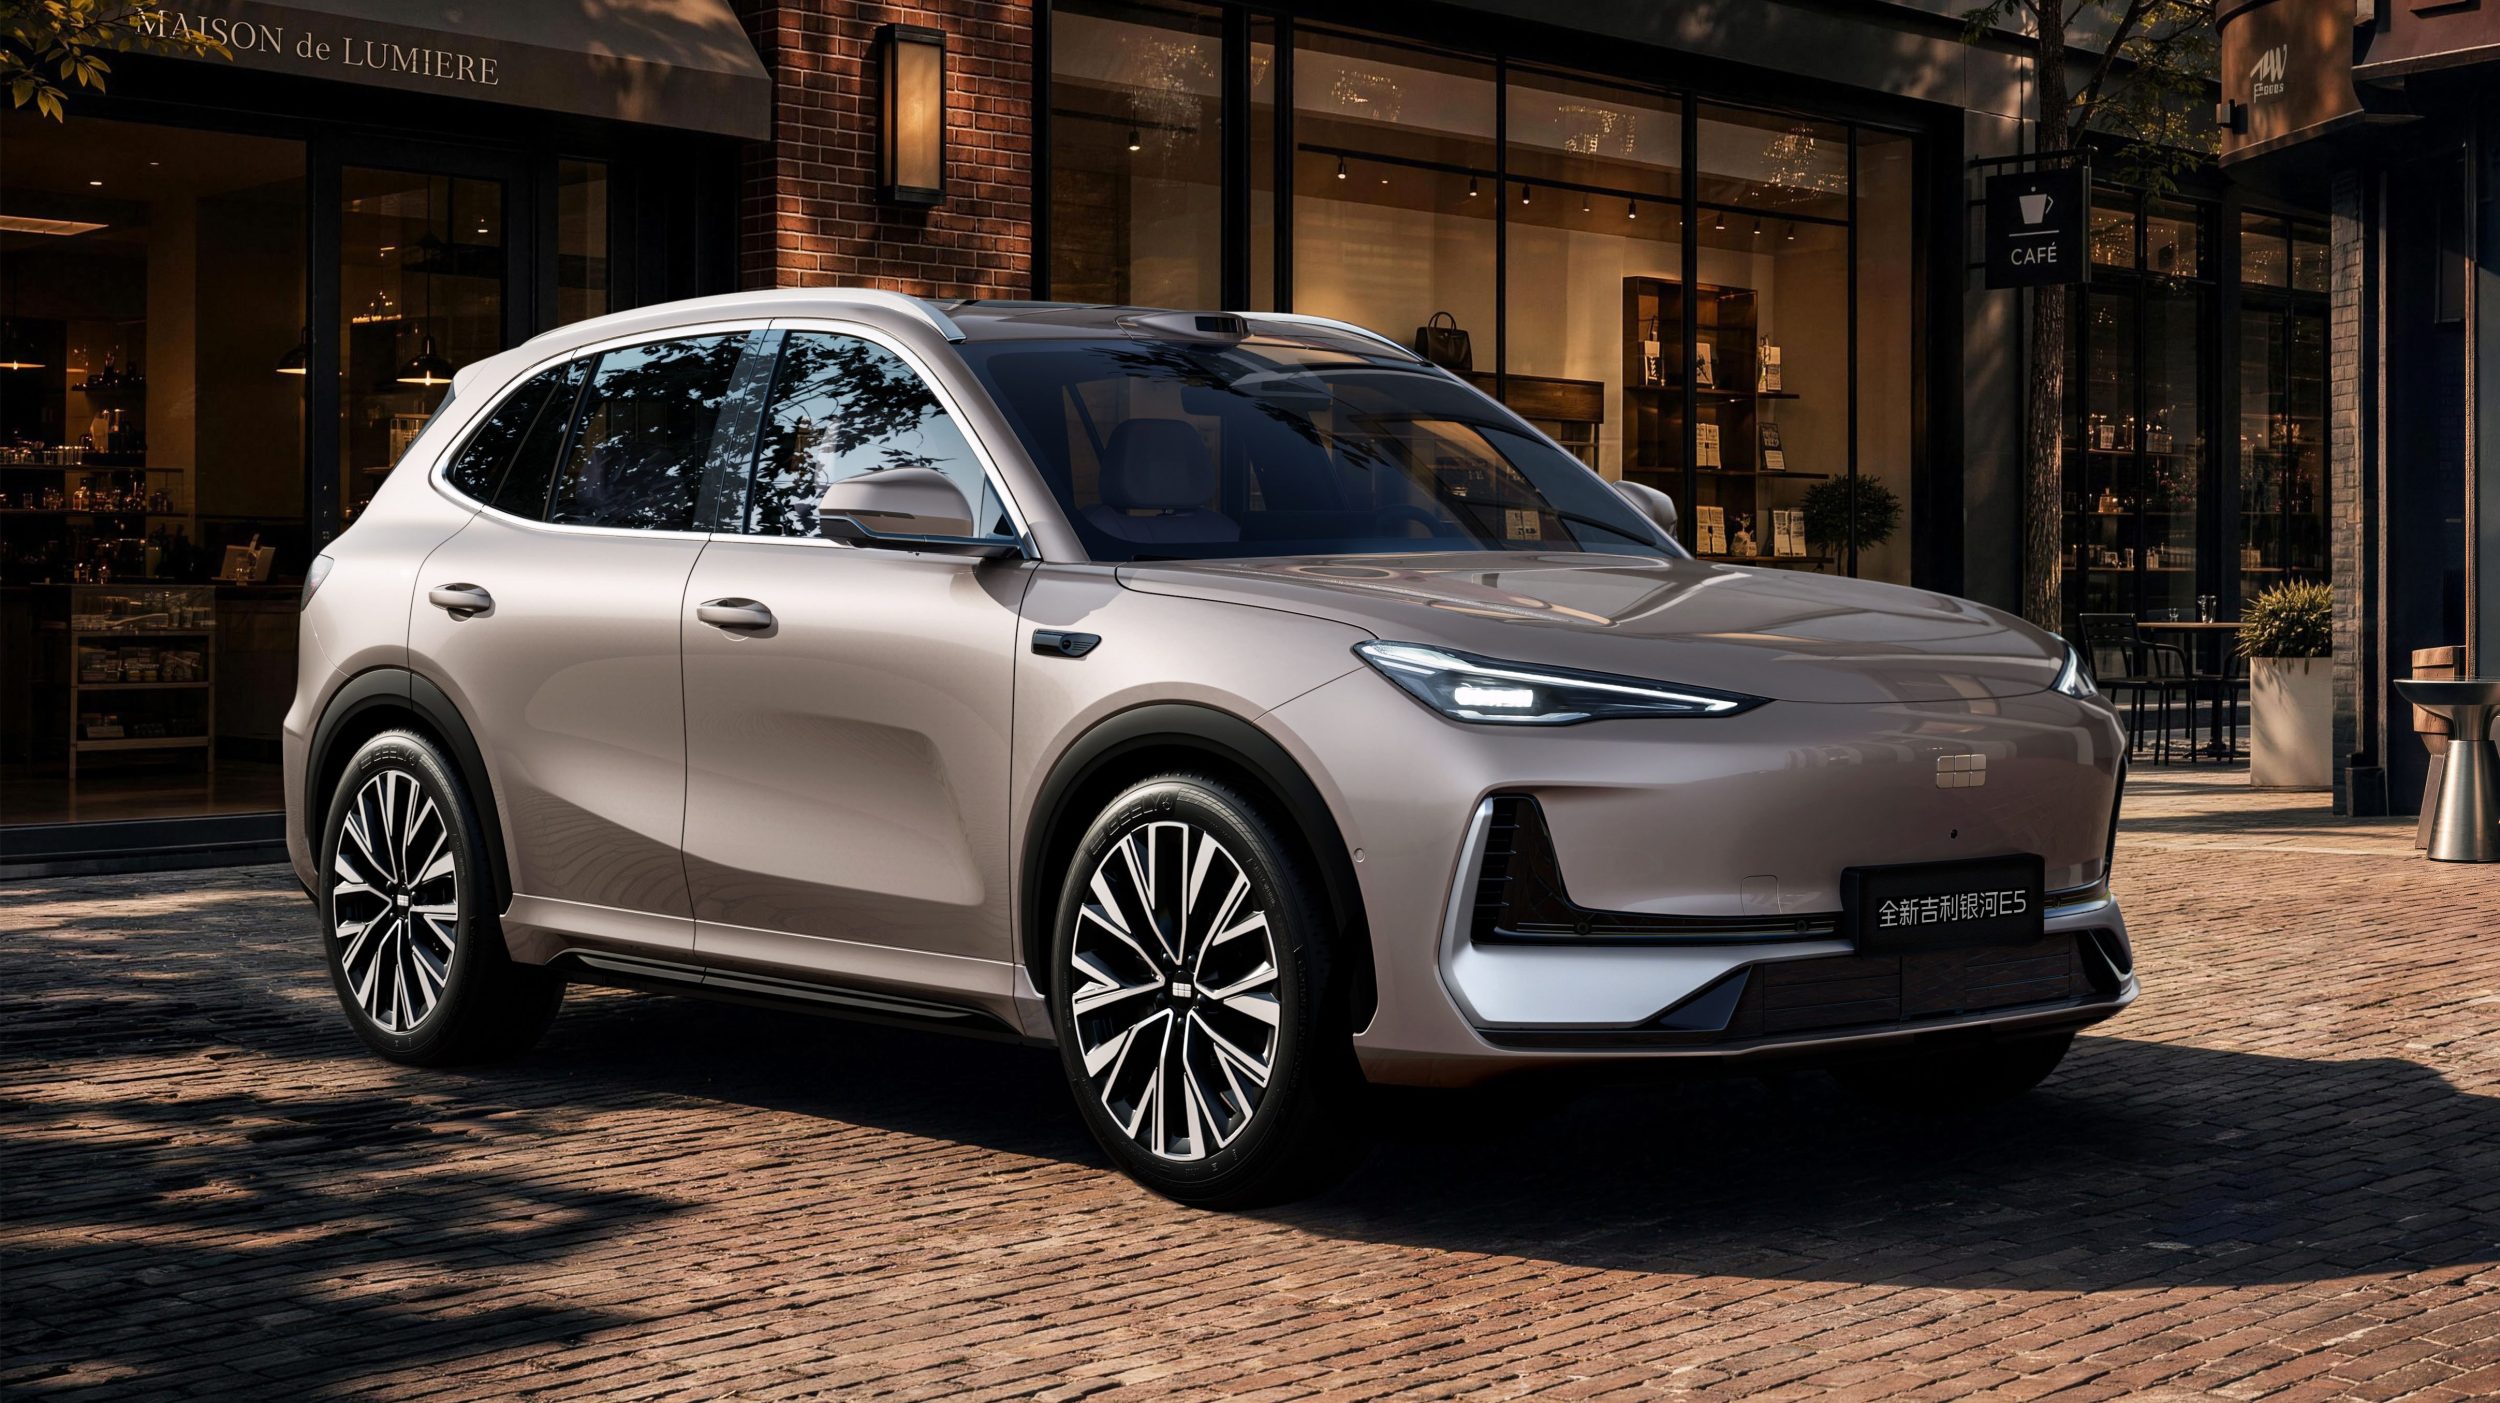
The Geely group remained the largest Chinese automotive group in Europe by volume.

Its European registrations reached 25,971 units in August, up 25.1% YoY, while the January-August total stood at 289,128 units, up 11.6%.
The figure includes Chinese brands such as Geely Galaxy, Lynk & Co and Zeekr, as well as overseas brands under the group, including Volvo, Polestar, smart and Lotus.
Chery, including Chery, Jaecoo, Jetour and Omoda, recorded 22,668 European registrations in August, up 217.5% YoY. Its January-August total reached 207,871 units, up 279.7%.
SAIC also continued to grow, with European registrations reaching 21,214 units in August, up 32.4% YoY. Its registrations for the first eight months totaled 230,290 units, up 19.7%.
Tesla also returned to growth in the European market, with August registrations reaching 15,430 units, up 4% YoY.
Performance among traditional European automakers was mixed. Mercedes-Benz grew 7.6% in August and Stellantis increased 3.5%, while Volkswagen Group declined 3.6% and Renault Group fell 4.4%.
Part of Stellantis’ growth came from its distribution partnership with Leapmotor.
ACEA data showed that Stellantis and Leapmotor together held a 15.6% share of the EU, EFTA and UK markets in January-August.
Discover more from ChinaEVHome
Subscribe to get the latest posts sent to your email.