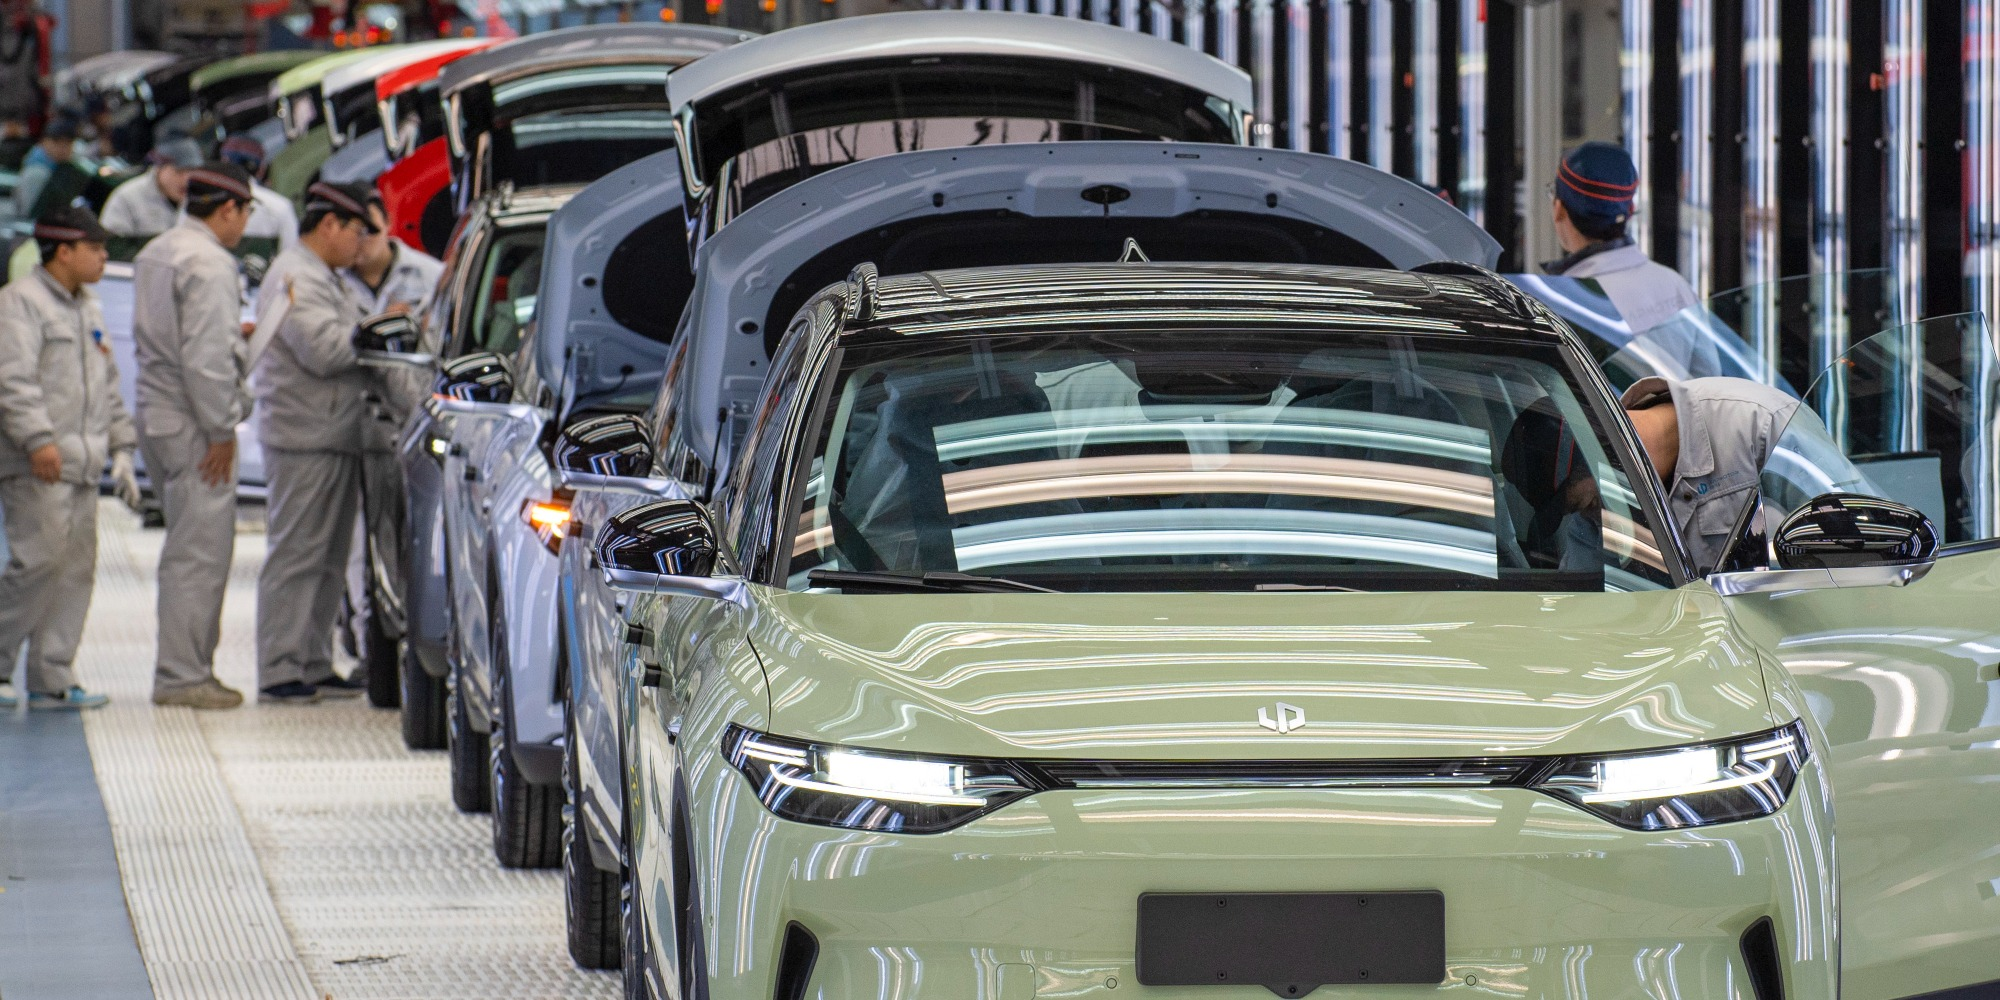
The sales volume in the new energy market was approximately 976,000 vehicles, up 10.5% yoy and down 12.1% mom, performing slightly better than the overall market.
On September 4, the China Passenger Car Association (CPCA) released its analysis report on China’s new energy vehicle (NEV) market for July 2025.
Data shows that the overall sales volume in China’s passenger vehicle market reached 1.843 million units in July, a year-on-year increase of 1.5% but a month-on-month decrease of 13.9%.
Among these, NEV sales reached approximately 976,000 units, up 10.5% year-on-year but down 12.1% month-on-month. NEVs accounted for 53.0% of total passenger vehicle sales, performing slightly better than the overall market.

In terms of specific energy types, pure electric vehicle (BEV) sales reached about 611,000 units in July, surging 25.0% year-on-year but declining 9.6% month-on-month. Plug-in hybrid electric vehicle (PHEV) sales were around 365,000 units, down 7.5% year-on-year and 15.8% month-on-month.
Furthermore, the sales from the top 10 cities for NEVs in July accounted for 25.5% of the national total, a decrease of 0.4 percentage points from 25.9% the previous month. The top three cities were Beijing, Chengdu, and Shanghai. Ningbo and Hangzhou entered the top ten, replacing Tianjin and Xi’an.
From the perspective of NEV penetration rate, the top 10 cities all exceeded a 50% penetration rate this month. The top three cities were Shenzhen (66.2%), Ningbo (64.0%), and Wuhan (62.1%). The city with the lowest penetration rate among the top ten was Chengdu (54.3%).

From the perspective of the pure electric vehicle segment, the A0-class, B-SUV, and A-SUV were the most popular segments, accounting for 18.4%, 15.0%, and 15.0% of sales, respectively. The report indicated that compared to the previous month, the market share of C-SUVs increased relatively significantly (+1.1 percentage points) due to the rapid growth in deliveries of the YU7. Conversely, the market share of A-SUVs decreased relatively more (-1.3 percentage points).
Additionally, compared to the same period last year, the market share of C-SUVs expanded from 2.9% to 6.2%, while the market share of A-class vehicles contracted from 12.4% to 7.8%.

On July 7, four departments—the National Development and Reform Commission, the National Energy Administration, the Ministry of Industry and Information Technology, and the Ministry of Transport—jointly issued the “Notice on Promoting the Scientific Planning and Construction of High-Power Charging Facilities.” The notice proposes further optimizing and improving the layout of China’s charging facility network, aiming to steadily build a high-power charging infrastructure system that is rationally planned, features upgraded quality, and utilizes advanced technology.
Discover more from ChinaEVHome
Subscribe to get the latest posts sent to your email.


