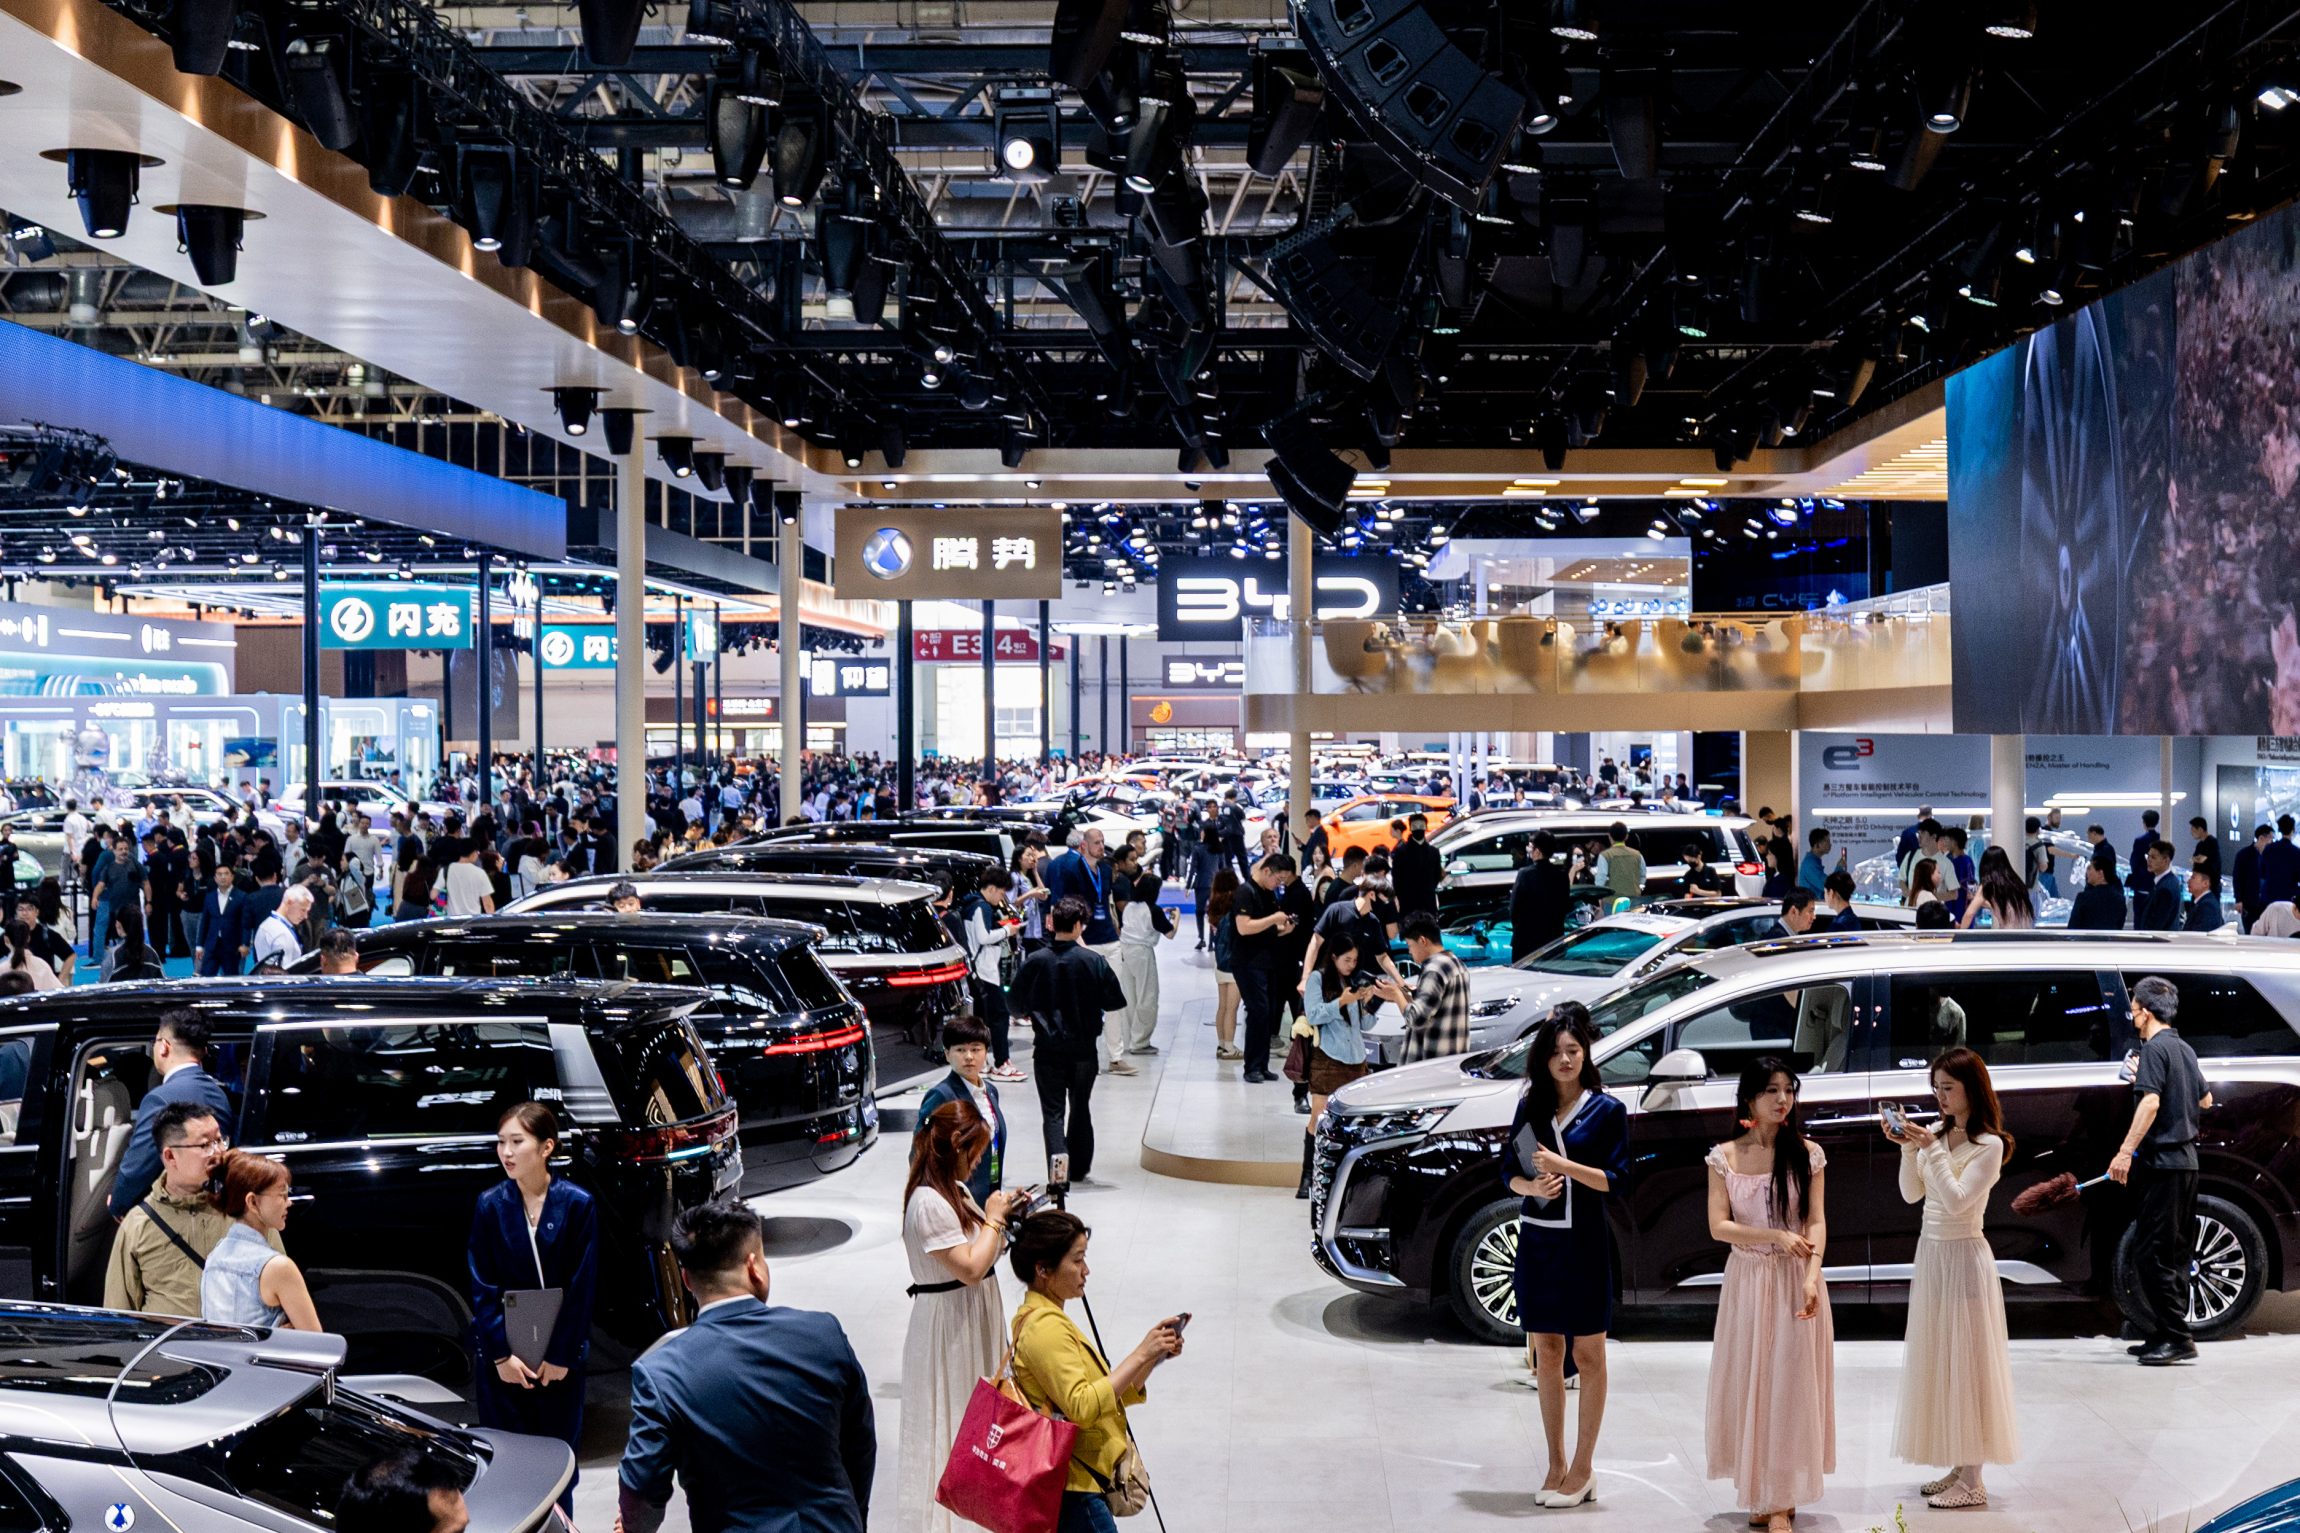
- China’s retail slump through Sept. 1–13 — down 23% YoY to 515K units — reflects weak demand and dealers’ need to use promotions and local incentives to counter high seasonal comparison effects.
- NEV strength persists: NEV retail sales were 362K units (down 10% YoY, up 16% MoM) and NEV wholesale sales were 411K units (up 1% YoY, up 26% MoM), with NEVs comprising 70.3% of retail and 74.7% of wholesales.
- ICEs face sharp contraction versus EVs, with pure gasoline production down 51% YoY to 215K units and hybrids down 20% to 174K units, raising execution risks around inventory destocking, subsidy cliffs and margin pressure.
China passenger car retail sales reached 515K units from September 1 to 13, down 23% YoY but up 4% from the same period in August, data from the China Passenger Car Association (CPCA) showed.
For the year to date, passenger car retail sales totaled 12.231M units, down 21% YoY.
Wholesale sales also weakened. Passenger car manufacturers sold 550K units in the first two weeks of September, down 22% YoY but up 22% MoM. Cumulative wholesale sales reached 17.733M units this year, down 6% YoY.
The market showed some sequential recovery as China entered the traditional “Golden September and Silver October” sales season. However, strong purchase activity triggered by subsidy policies last year created a high comparison base, keeping YoY pressure elevated in September.

NEVs remained the biggest source of structural growth despite the broader market slowdown.
NEV retail sales totaled 362K units from September 1 to 13, down 10% YoY but up 16% from the previous month. Cumulative NEV retail sales reached 7.036M units this year, down 12% YoY.
On the wholesale side, NEV sales performed better. Manufacturers wholesaled 411K NEVs during the period, up 1% YoY and 26% from the same period in August. Year-to-date wholesale sales reached 10.189M units, up 9% YoY.
NEVs accounted for 70.3% of passenger car retail sales and 74.7% of manufacturer wholesale sales in the first two weeks of September. The segment is shifting from an incremental growth market into a key force reshaping China’s entire auto industry structure.
Meanwhile, traditional ICE vehicle sales continued to face pressure.

Pure gasoline vehicle production totaled 215K units in the first two weeks of September, down 51% YoY. Production of hybrid and plug-in hybrid models fell 20% YoY to 174K units.
With rising fuel costs, stronger EV competitiveness, and expanding NEV offerings, the market space for traditional combustion-engine vehicles continues to shrink.
The CPCA said the September auto market will receive support from local consumption incentives, automaker promotions, and the continued ramp-up of recently launched models during the peak sales season.
However, demand remains uncertain as last September saw a surge in purchases ahead of the expiration of some regional subsidies, creating a high comparison base. Rising fuel prices are also weighing on consumer interest in gasoline vehicles, with domestic gasoline prices increasing by more than RMB 830 per ton cumulatively since late July.
Discover more from ChinaEVHome
Subscribe to get the latest posts sent to your email.