- ZF plans significant layoffs, targeting the E-Mobility division due to slow EV adoption in Europe, mirroring struggles faced by Bosch.
- The German automotive industry is witnessing drastic job losses amid fierce competition from China.
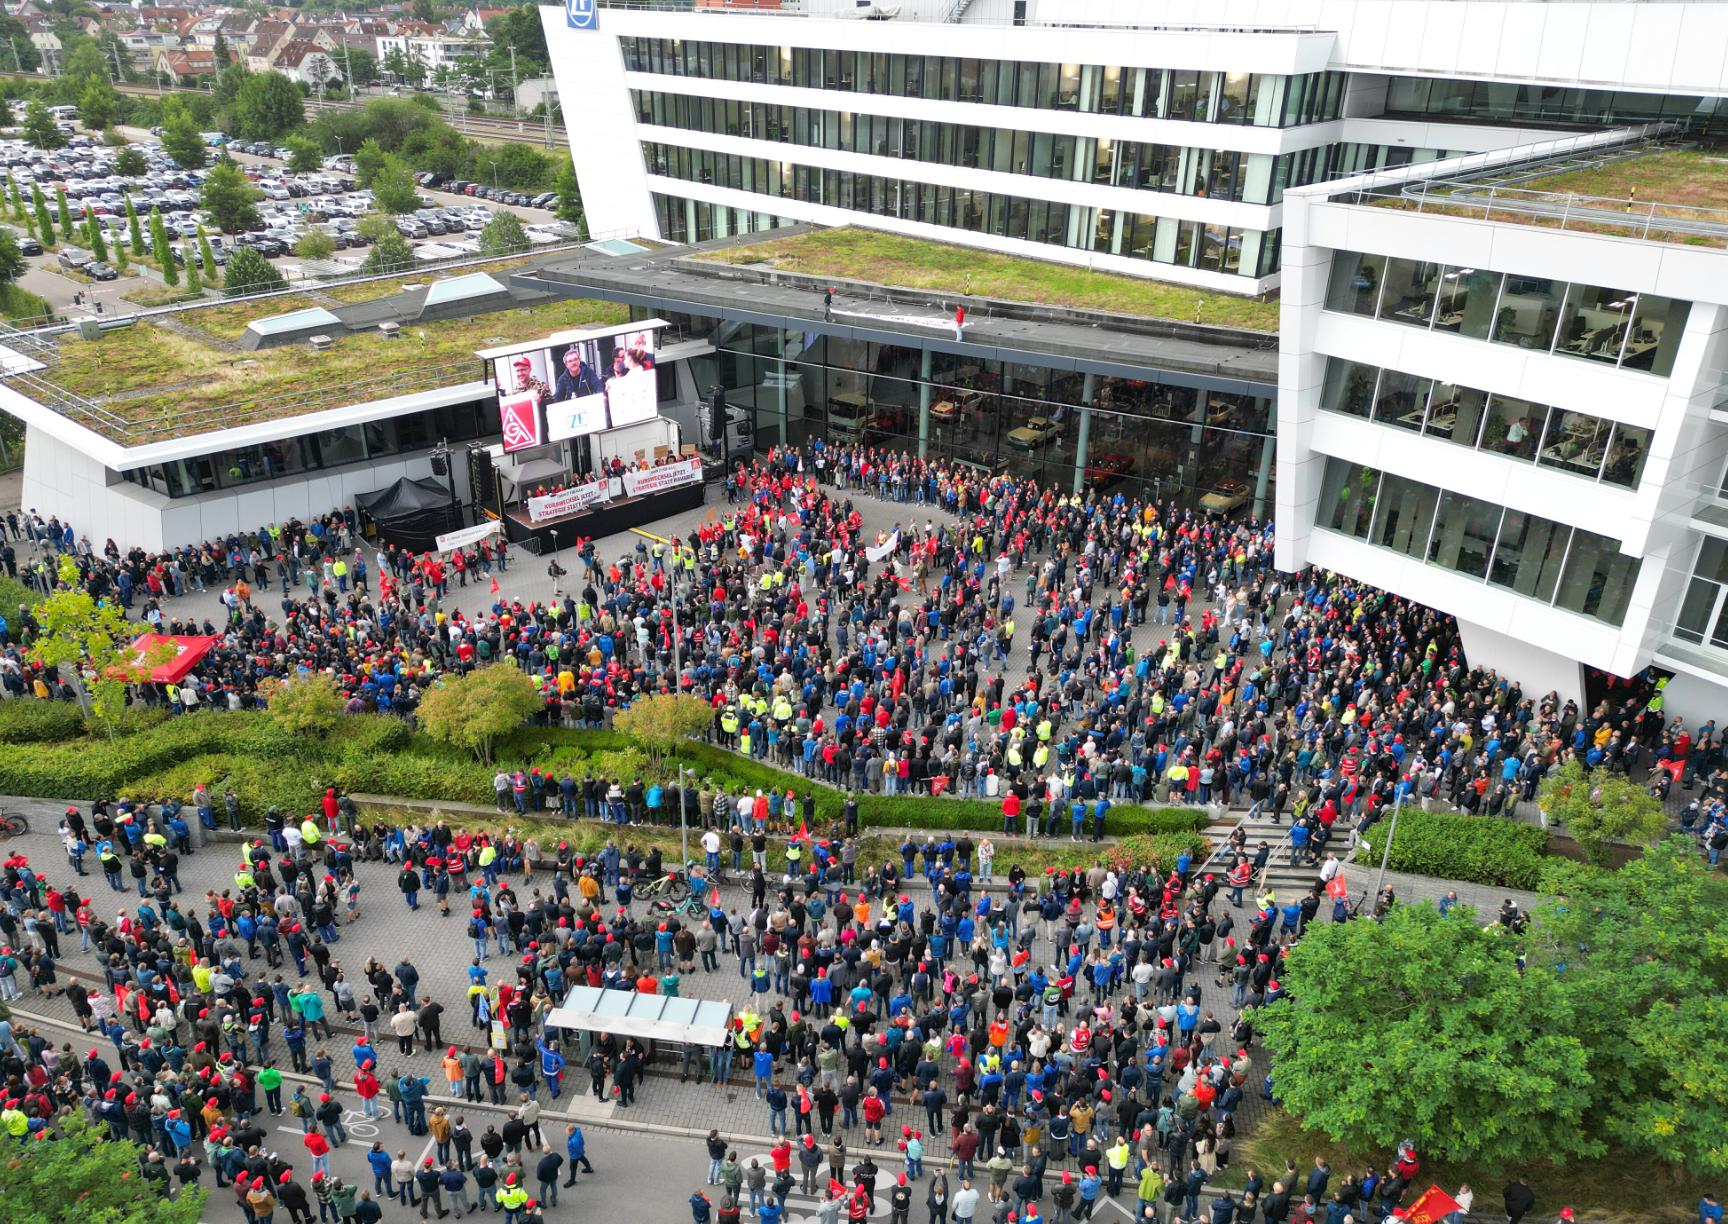
In July this year, 12,000 ZF employees took to the streets to protest against the company’s proposed layoff policy.
The latest report from Forbes indicates that ZF has finalized a specific downsizing plan, which will first target its E-Mobility Division, cutting 7,600 local employees. By 2028, ZF plans to lay off a total of 11,000 to 14,000 employees, accounting for 25% of its total workforce in Germany.

According to Forbes, ZF is merely “following in Bosch’s footsteps.”
As a top global automotive parts supplier, Bosch announced in 2024 that it would lay off 9,000 employees and plans to cut another 13,000 jobs by 2030.
Bosch stated that it aims to reduce operating costs through layoffs. By cutting approximately 22,000 employees in Germany, Bosch’s automotive division is expected to save more than 2.5 billion euros (about 20.6 billion yuan).
If Germany’s largest and second-largest automotive suppliers are struggling like this, mid- and downstream enterprises in the industry are having an even harder time.
The AE Group, which produces aluminum castings for white bodies and gearboxes, has announced bankruptcy and suspended operations; Kiekert, a company with a 165-year history specializing in automotive door locks, has also declared bankruptcy, putting the jobs of more than 1,000 employees at risk.
Looking back at Germany’s entire automotive industry over the past year: Volkswagen announced 35,000 layoffs, Mercedes-Benz 40,000, Audi 7,500, and Ford Germany 2,900.
Macro data is also very worrying: as of July, industries in Germany closely related to the automotive sector, such as metalworking, electronics, steel, and manufacturing, have lost 270,000 jobs year-on-year. Germany’s industrial output fell by 4.3% month-on-month in August, while the output of the automotive industry dropped by 18.5% month-on-month.
Based on this series of developments, an industry analyst with 140,000 followers on an overseas social platform opined, “The German economy is not in a crisis; it is collapsing.”

Media outlets including Forbes and AFP all believe that “failed EV transition” and “encroachment by Chinese competitors” are the main causes of the overall collapse of Germany’s automotive industry.
However, from the “criticism and condemnation” of overseas netizens, it is evident that there may be deeper-seated reasons.
“New Energy Transition” Becomes a Pipe Dream
In its layoff announcement, ZF clearly stated that the direct reason for closing relevant departments and cutting employees is that “the popularity of pure electric vehicles (EVs) in Europe is far lower than expected.” In the future, ZF will allocate more resources to the development of parts related to plug-in hybrid vehicles.
As one of the regions most aggressively promoting the new energy transition globally, Europe previously set a long-term goal of completely banning the sale of fuel-powered vehicles by 2035; its medium-term target is to have at least 30 million electric vehicles on the road by 2030, in an effort to further reduce carbon dioxide emissions.
This legislation was approved in 2023 and passed by the European Parliament in February 2025, meaning that the new energy transition of Europe’s automotive industry will be strictly restricted by a legal framework.
For this reason, major brands in the European market have also put forward corresponding new energy vehicle transformation plans.
For example, Volkswagen once planned that by 2030, pure electric vehicles would account for more than 80% of its sales in the European market; BMW hoped that pure electric vehicles would account for more than 50% of its sales by 2030, while Mercedes-Benz aimed to “achieve full electrification by 2030.”
However, as ZF pointed out, the popularity of pure electric vehicles in the European market is indeed far lower than expected.
Slow Popularization
From a data perspective, in Q1 2025, sales of pure electric vehicles in Europe’s five major markets (the UK, Germany, France, Italy, and Spain) increased by 30.7% year-on-year, and their market share reached a “record high” of 15.4%; according to statistics from domestic media, the penetration rate of pure electric vehicles across the entire European region in Q1 was 15.2%.

For reference, it is estimated that the penetration rate of pure electric vehicles in China in Q1 2025 was approximately 25% (during the same period, the penetration rate of new energy vehicles was 41.2%, and pure electric vehicle sales accounted for about 61.2% of new energy vehicle sales), which is significantly higher than that of the European market.
Furthermore, the acceptance of pure electric vehicles in the European market is highly differentiated, with Nordic countries showing much higher acceptance than Eastern and Southern European countries or regions. At the same time, government subsidies for new energy vehicles in many European countries are gradually being phased out, making the popularization of pure electric vehicles even more difficult.
From the comments of users on overseas social platforms, they also disdain a series of “carbon neutrality” initiatives implemented in Europe, even describing them as “economic suicide by the West.”
Lacking a mass base and, even more so, the material foundation of energy supplement infrastructure such as charging stations, Europe is destined to have a bumpy road in popularizing pure electric vehicles.
Under pressure, major brands have had to adjust their corresponding transformation goals simultaneously. Mercedes-Benz is the most representative example, having announced the postponement of its “full electrification by 2030” goal to “new energy (including hybrid) vehicles accounting for 50% of sales by 2030.”
Other automakers have taken similar approaches, acknowledging that fuel-powered vehicles still play a crucial role in the market, and that the era truly belonging to pure electric vehicles has not yet arrived so soon.
All Efforts in Vain
The dark humor lies in the fact that leading suppliers, which were once skilled in developing complex core components such as gearboxes, have invested substantial funds in researching and developing corresponding components and building production lines to keep up with the new energy transformation of automakers.
At its headquarters in Germany, Bosch previously invested 77 million euros in its Schwäbisch Gmünd R&D center to develop peripheral solutions for high-voltage battery packs; in 2018, it announced the construction of a chip factory in Dresden for manufacturing “electric mobility processors,” with a total investment of 1 billion euros—Bosch’s largest single investment in its history.
On ZF’s side, in 2018, it announced a global investment of 23.8 billion yuan to lay out the new energy vehicle market. For electric drive gearbox technology alone, it invested approximately 6.3 billion yuan to upgrade its Saarbrücken factory, located in Germany’s home base.
More ironically, as mentioned at the beginning of the article, the “E-Mobility Division,” which is facing 7,600 layoffs, was one of ZF’s most important investments. As early as 2019, ZF spent 30 million euros to build a new office building for this division.
In ZF’s downsizing plan, the original fate of the E-Mobility Division was to be split and dissolved, so the current outcome of “only 7,600 layoffs” is already a more fortunate one.
Marco Zesch, head of Bosch’s Electric Mobility Division, told AFP, “The slower-than-expected popularity of electric vehicles means we have significant overcapacity, especially in Europe, and particularly in Germany.”
As one overseas netizen described it, “The goals set for electric vehicles and manufacturers are destroying automotive companies.”

This is undoubtedly one of the core reasons. As for the other reason, it is also more frequently mentioned by mainstream media—Germany’s major Chinese clients are constantly being lost, and they also have to face challenges from Chinese competitors.
Supply Chain Competition from China
Reports from Forbes, AFP, and other media have all mentioned this view, and the fact is indeed the case—the rapidly emerging local Chinese supply chain has already posed a threat to traditional supply chain giants to a certain extent.
These reports further note that one of the reasons for this “threat” is the “price war” that has become very prevalent in the Chinese market in recent years, which has significantly squeezed the profits of parts suppliers.
Speaking of this, some readers may recall a series of reports by Electric Planet in 2024: a leading domestic automaker was deeply involved in a controversy over “requiring suppliers to reduce prices on their own.” The Chinese consumers are well aware of the series of butterfly effects caused by the “price war.”

At the same time, Chinese automakers are major clients of suppliers like Bosch; China is one of Bosch’s four largest single markets.
Affected by this, according to Bosch’s 2024 annual report, its full-year profit margin was approximately 3.5%, with earnings before interest and taxes (EBIT) of 3.2 billion euros, a year-on-year decline of 30%. This significant drop in profits is the direct reason for Bosch’s launch of layoffs in 2025.
“Price competition” is only one of the reasons. In recent years, the strong rise of China’s supply chain has also brought severe challenges to multinational parts suppliers such as Bosch.
The rise of China’s supply chain has been accompanied by the rapid development of China’s new energy vehicles. In pursuit of higher efficiency, more and more automakers have begun to extensively cooperate with local Chinese supply chain enterprises—not only Chinese local automakers but also a considerable number of joint-venture and foreign-funded automakers selling new energy vehicles in China.
According to a report from CounterPoint Research, the “localization rate” of China’s new energy vehicle industry in the first half of 2025 exceeded 90%; when broken down by specific brands, the “localization rate” of local brands such as NIO ranges from 92% to 95%, while the localization rate of Tesla’s Model 3/Model Y produced at its Shanghai Gigafactory has exceeded 95%.
The continuous increase in the “localization rate” of automakers in the Chinese market is not only due to the “price” factor but also the change in game rules. Simply put, products provided by established parts suppliers such as Bosch and ZF can no longer fully meet the design needs of current new energy vehicles.
In the era of fuel-powered vehicles, Bosch’s spark plugs, fuel injectors, electronic fuel injection technology, and ESP (Electronic Stability Program) were key components that most automakers could not do without. However, with drive motors replacing internal combustion engines, power battery packs replacing fuel tanks, and gearboxes disappearing—traditional parts suppliers’ electrified components have not achieved the expected competitiveness.

Let’s look at the “localization rate” of specific core components. In the most critical field of power battery-related components, the localization rate of cathode materials reaches 93%, anode materials 98%, separators 90%, and electrolytes have taken the lead in achieving 100% localization.
When it comes to power batteries themselves, they have long been dominated by Chinese suppliers. In fields with relatively low localization rates, such as high-power semiconductor chips and motor electronic control systems, traditional German supplier giants have also failed to gain a share.
These multinational supply chain enterprises actually had long anticipated such a development prospect. Therefore, starting around 2018, they invested heavily in transformation, hoping to continue their advantages in the field of core components for new energy vehicles.
However, in the European market, despite Bosch and ZF’s ambitions, the slower-than-expected progress of the new energy transition has left their efforts unused; in the Chinese market, although the market conditions are favorable, they cannot compete with local supply chain enterprises.
In the final analysis, it all boils down to one sentence: “To forge iron, one must be strong oneself.”
To Forge Iron, One Must Be Strong Oneself
Suppliers and automakers have always been closely interdependent, sharing weal and woe.
Whether it is suppliers or automakers, the once dominant German giants are now facing difficulties. Although there are objective factors such as the general environment, the fundamental reason is the decline in their own competitiveness.

Many overseas netizens have clearly recognized this. Based on facts, German automakers and suppliers have indeed been less quick and decisive in the process of electrification transformation, especially when compared with Chinese local automakers and suppliers.
The lag in strategy and technology has directly led to backwardness in product experience.
An overseas netizen commented under a relevant report, stating that they used to drive a “Mercedes-Benz G-Class” but now drive an electric vehicle from a Chinese brand. They also added, “No other car can be more comfortable than it.”

While such subjective opinions cannot represent the true situation of Germany’s automotive industry, they can reflect from the side that the product experience of Chinese new energy vehicles has been greatly improved, and the advantages of German automotive products are no longer as obvious as they were in the era of fuel-powered vehicles.
For German automakers, they still have a chance to “stage a comeback.”
By the end of this year, the new generation of pure electric vehicles from Mercedes-Benz, BMW, and Audi will be launched globally. With new models such as the all-electric CLA, the new-generation BMW iX3, and the Audi Q6L e-tron taking the lead, the BBA (BMW, Mercedes-Benz, Audi) brands will launch a new round of challenges against Chinese competitors.
Considering that the new generation of overseas brand electric vehicles is all built on brand-new pure electric platforms, with significantly improved three-electric (battery, motor, electronic control) performance, if these new models are priced reasonably, they are believed to change the current market pattern to a certain extent.
However, for German suppliers, from the perspectives of technical routes and core component performance, there is no sign of a similar “counterattack” for the time being.
Moreover, for the new generation of pure electric vehicles from German automakers, except for core components developed in-house, other key technologies, such as intelligent driving, tend to adopt solutions from China rather than cooperating with traditional multinational suppliers like Bosch.
The inability to make achievements in the new energy vehicle field means that these parts suppliers will lose “incremental growth.” Relying on the large base of fuel-powered vehicles, they will not face an existential crisis anytime soon, but they seem to have entered an unfavorable trajectory.
“Slow death” is also equally terrifying for traditional parts giants.
(End)
Discover more from ChinaEVHome
Subscribe to get the latest posts sent to your email.